Introducing the American Investor Initiative
Premium domains for sale
Freedom Is Back In Style
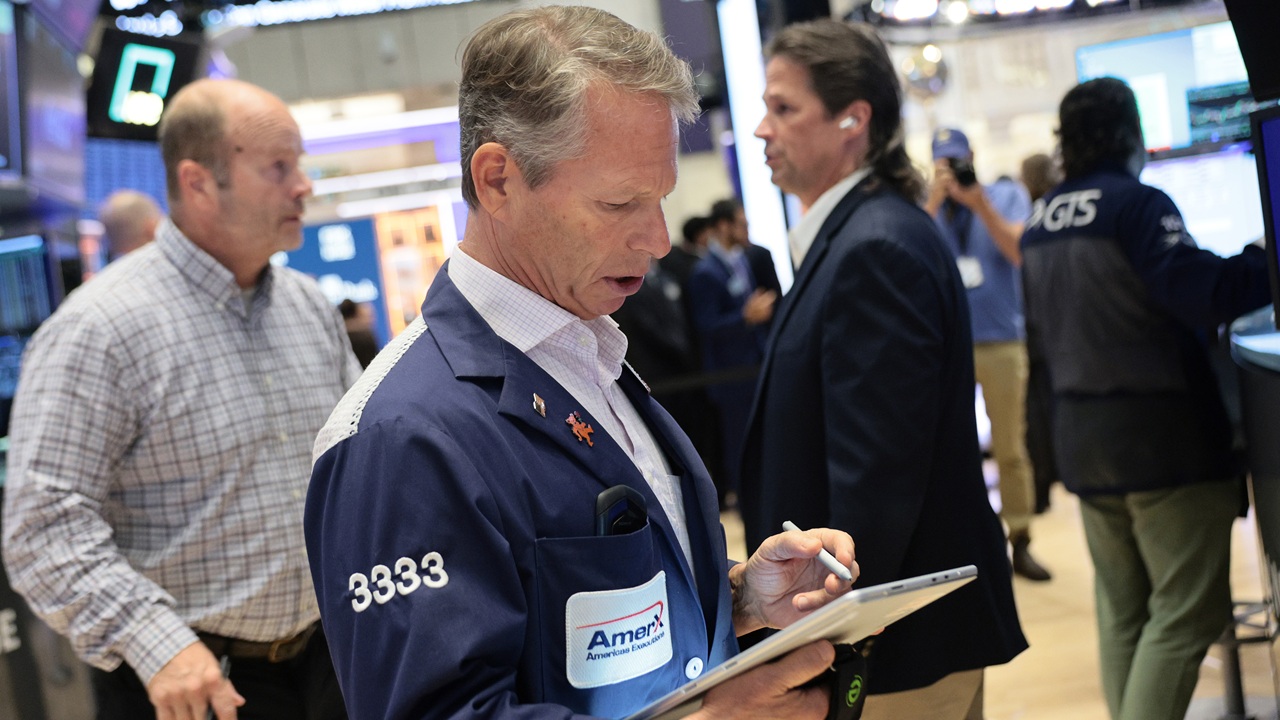
The Heritage Foundation’s Free Enterprise Initiative is now the American Investor Initiative, a name that says plainly what its predecessor implied: that the American economy runs to no small degree on the decisions of ordinary people who own shares—in their 401(k)s, their pension funds, their modest brokerage accounts—and who have a personal stake in how the companies they own are governed.
Freedom Is Back
In Style
Premium domains for sale
It says, too, that the health of American capital markets is not a niche concern for men in Brioni suits but a pillar of national strength, on par with the size of the Navy. China’s capital markets, for all Beijing’s ambitions, remain hobbled by capital controls, a state-directed banking system given to intervening in market downturns through its so-called national team, and corporate structures built to obscure rather than clarify who actually owns what.
A country whose markets are transparent, adjudicated by independent courts, and governed by the rule of contract rather than the whim of the party enjoys an advantage that compounds, like interest, over decades. That advantage is worth guarding jealously, and guarding it from ideological capture at home is no less urgent than guarding it from Beijing abroad.
Heritage’s own portfolio (shares in more than a thousand companies) is the vehicle for this work, and the results, quietly achieved, have been substantial: Half of last season’s shareholder proposals were withdrawn, not because Heritage lost interest but because the companies in question agreed, in private conversation, to change course.
Some of our proposals went to a shareholder vote and received modest support, including at Starbucks and Amazon. But those public tallies capture only a fraction of what happens in shareholder engagement. The real measure of success is more often what happens before a proposal ever reaches the ballot.
Low vote counts should not be misrepresented as a proxy for overwhelming shareholder consensus. On highly divisive issues, a 1% vote for an anti-DEI or anti-ESG proposal does not establish that 99% of shareholders affirmatively support DEI or ESG—particularly when a corresponding proposal advancing the opposite position receives similarly low support, sometimes on the same ballot.
Treating such results as evidence of near-universal shareholder support is analytically unsound and risks conflating non-support for one proposal with affirmative support for its opposing position (see here and here). More broadly, these outcomes raise legitimate questions about whether proxy voting results accurately capture the views of beneficial owners or instead reflect structural features of the proxy voting system.
For a generation, the Left treated the shareholder proposal as its preferred instrument of moral suasion, using it to embed progressive commitments into the machinery of the corporation itself (its hiring practices, marketing, compensation formulas, charitable giving, and health care plans) until institutions that owed their existence to serving shareholders found themselves administering a kind of parallel social policy.
Our engagement targets last season were representative rather than exhaustive: DEI mandates folded into executive pay, ESG substituted for the ordinary discipline of return on investment, corporate charitable giving keyed to the Southern Poverty Law Center’s contested “hate map,” health plans extending gender transition treatment to minors.
Each was a symptom of a broader condition: the decades-long repurposing of shareholder capitalism.
The Right’s recent response—which was long past due—has been to do the same work in reverse, not by picketing shareholder meetings but by talking, company by company, to the men and women who run them.
We approach our engagements in hopes of improving firms, not of remaking them as political agents for our own side. Shareholders, after all, profit when their companies succeed, and the scorched-earth activist investor is usually a poor steward of his own portfolio.
All of this occurs against a backdrop that may soon shift beneath everyone’s feet. On Sept. 16, the Securities and Exchange Commission formally proposed rescinding Rule 14a-8, the 1942-vintage regulation that obliges public companies to include qualifying shareholder proposals in their proxy statements. Chairman Paul Atkins suggested that the commission has been legislating without a permission slip from Congress, and that nothing in the Securities Exchange Act authorizes the SEC to decide which resolutions are a “proper subject” for a shareholder vote.
Kudos to Atkins for recognizing federal overreach and its net deleterious impact on public firms. Had the rule been rescinded decades ago, a great deal of institutionalized progressivism might never have taken root in corporate America in the first place. But regret is a poor substitute for strategy, and the sounder response to belated vindication might be to get on with the work the vindication makes possible, at least for a little longer.
The proposal, it bears repeating, is not yet law; it sits in a 60-day comment window, and formal adoption remains ahead. This is not obviously positive, in the near term, for the conservatives now enjoying real momentum with their shareholder engagement.
Once finalized, the rule’s rescission would relocate the whole enterprise of shareholder engagement from a single federal rulebook to 50 state corporate codes and thousands of individual sets of bylaws (a jurisdiction, in practice, concentrated overwhelmingly in Delaware, with Nevada and Texas gaining ground as companies conduct what has been dubbed “DExit,” and Wyoming a less assuming beneficiary further behind).
A brief transition period (two years, say) would let these states write the statutory machinery this shift requires. The absence of such preparation invites exactly the kind of procedural chaos that gives reform a bad name.
The next front, meanwhile, is perhaps even more consequential: state pension funds. An audit of how red-state pension systems have actually voted their proxies would likely turn up a good deal of daylight between the professed values of the states holding those funds and the votes their money managers have been casting on their behalf.
Fixing that gap, aligning the fiduciary conduct of red-state pension funds with the values of the citizens whose retirements they administer, is unglamorous work that generates no headlines and considerable friction. But it’s necessary.
The American investor isn’t an abstraction, although abstractions have been making decisions for him for years. He is, rather, the worker whose 401(k) owns a sliver of General Motors, the teacher whose pension owns a sliver of Microsoft, the retiree whose savings depend upon the prudence of people she will never meet.
Their ownership should mean more than a quarterly statement and a line on a balance sheet. Those who manage Americans’ investments must remember whose money they are managing, and whose interests they are obliged to serve.
That’s the modest proposition behind the American Investor Initiative: Capitalism becomes an odd thing when the people who own the capital have the least to say about how it is used.
More from this network:
Domains for Sale · GOTPeople.org · TheDSAPlatform · The Truth About Socialism
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
I am just an average American. My teen years were in the late 70s and I participated in all that that decade offered. Started working young, too young. Then I joined the Army before I graduated High School. I spent 25 years in, mostly in Infantry units. Since then I've worked in information technology positions all at small family owned companies. At this rate I'll never be a tech millionaire. When I was young I rode horses as much as I could. I do believe I should have been a cowboy. I'm getting in the saddle again by taking riding lessons and see where it goes.
Premium domains for sale
Comments (0)